Purpose and Principles of Taxation

100% found this document useful (2 votes)
9K views5 pages
This document defines taxation and distinguishes it from other forms of exactions. It states that taxation is an enforced proportional contribution imposed by the state to support the government. The three main purposes of taxation are to raise revenue, regulate activities, and promote general welfare. Taxes are distinguished from license fees and special assessments. License fees are imposed under the police power for regulation, while taxes are imposed under the taxing power for revenue. Special assessments only apply to land and are based on benefits from public improvements.
License
© All Rights Reserved
We take content rights seriously. If you suspect this is your content, claim it here.
Available Formats
Download as DOCX, PDF, TXT or read online on Scribd
  • General Principles of Taxation
  • References and Citations

I.

GENERAL PRINCIPLES

A. Concept and Purpose of Taxation

1. Definition

Taxation is the act of laying a tax. It is a process or means by which the sovereign, through its
law-making body, raises income to defray the necessary expenses of government i. Further, it is an
enforced proportional contribution imposed by the State by its sovereign capacity, to support the
governmentii.

As a power, taxation refers to the inherent power of the state to demand enforced contributions
for public purposes. Being inherent to the State, the right to impose taxes exists apart from the
constitution. The power of taxation is a symbiotic relationship whereby, in exchange for the protection that
the citizens get from the government, taxes are paid iii.

Taxes, on the other hand, are enforced proportional contributions from persons and property,
levied by the state by virtue of its sovereignty for the support of the government and for all its public
needs. iv

They are not arbitrary exactions but contributions levied by authority of law, and by some rule of
proportion which is intended to insure uniformity of contribution and a just apportionment of the burdens of
governmentv. They are also pecuniary in nature and payable in money.

Also, taxes are obligations created by law vi. Taxes are never founded on contract or agreement,
and are not dependent for their validity upon the individual consent of the persons taxed vii. Taxes are
proportional in character, since taxes are based on one's ability to pay.

In addition, taxes are only levied by the state which has jurisdiction over the person or property.
Thus, the object to be taxed, must be subject to the jurisdiction of the taxing state before it can be
enforced. The power to tax cannot reach over into another jurisdiction to seize upon person or property
for purposes of taxation.

Further, it can only be levied by the law-making body of the state, being a legislative power,
through the enactment of tax statutes. Hence, it cannot be imposed by the executive department nor by
the courts. Also, as taxation involves a charge or burden imposed to provide income for public purposes,
the revenues derived from taxes should be for the exclusive benefit of the public and not for private
persons.

Basically, there are three elements of taxation.

(1) It is an enforced proportional contribution from persons and properties;

(2) It is imposed by the State by virtue of its sovereignty;

(3) It is levied for the support of the government viii.

Also, one of its nature and characteristic is that, (1) the State is free to select the subjects of
taxation and the court has repeatedly held that inequalities which result from a singling out of a particular
class for taxation or exemption infringe no constitutional exemption ix, (2) As the State has the power to
determine subjects of taxation, it is also free to select who will be exempt from Taxation x.

Lastly, taxes are personal to the tax payer. Hence, a company’s delinquency for instance, cannot
be enforced against its stakeholders as a corporation is given a distinct and separate personality by the
law form those persons who are composing it.

2. Purpose

Taxes are considered as the lifeblood of the State through which the government and its
agencies continue to operate and with which the State effects its functions for the welfare of the
constituents. Thus, their prompt and certain availability is an imperious need xi. It should be calculated
without necessary hindrance.

The rationale of taxation is graphically described by the Supreme Court in these words: “It is said
that taxes are what we pay for a civilized society. Without taxes, the government would be paralyzed for
lack of the motive power to activate and operate. Hence, despite the natural reluctance to surrender part
of one’s hard-earned income to the taxing authorities, every person who is able must contribute his share
in the running of the government. The government for its part is expected to respond in the form of
tangible and intangible benefits to improve the lives of the people and enhance their moral and material
values.” xii

Primarily, the following are the purpose of taxation:

A. Revenue  Basically the purpose of taxation is to provide funds or property with which the state
promotes the general welfare and protection of its citizens.

B. Regulation  It had also a regulatory purpose as in the case of taxes levied on excise or privilege
taxes like those imposed on tobacco and alcoholic products or amusement places like night clubs and
cockpits.

C. Promotion of General Welfare  In one case, the Supreme Court ruled that taxation may be used
as an implement of the police power in order to promote the general welfare of the people.

3. Tax v. other forms of exactions, distinction

It is important to differentiate taxes from other exactions especially when it comes to problems
and issues on double taxation, tax exemptions, and the jurisdiction of the Court of Tax Appeals. If an
exaction is not a tax, then the defense of a taxpayer, of double taxation will necessarily fail. A tax-exempt
individual or corporation is generally only exempt from paying tax; if the exaction is not tax, then the
individual or corporation must then still pay tax xiii

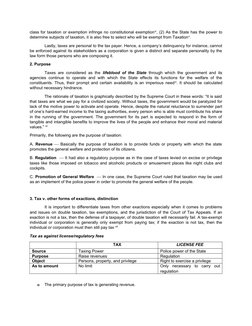
Tax as against license/regulatory fees

TAX LICENSE FEE


Source Taxing Power Police power of the State
Purpose Raise revenues Regulation
Object Persons, property, and privilege Right to exercise a privilege
As to amount No limit Only necessary to carry out
regulation

o The primary purpose of tax is generating revenue.


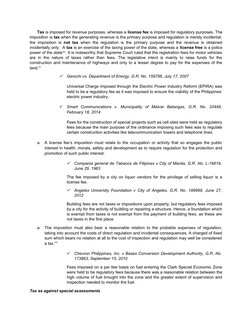
Tax is imposed for revenue purposes, whereas a license fee is imposed for regulatory purposes. The
imposition is tax when the generating revenue is the primary purpose and regulation is merely incidental;
the imposition is not tax when the regulation is the primary purpose and the revenue is obtained
incidentally only. A tax is an exercise of the taxing power of the state, whereas a license free is a police
power of the statexiv. It is noteworthy that Supreme Court ruled that the registration fees for motor vehicles
are in the nature of taxes rather than fees. The legislative intent is mainly to raise funds for the
construction and maintenance of highways and only to a lesser degree to pay for the expenses of the
[Link]

 Gerochi vs. Department of Energy, G.R. No. 159796, July 17, 2007

Universal Charge imposed through the Electric Power Industry Reform (EPIRA) was
held to be a regulatory fee as it was imposed to ensure the viability of the Philippines’
electric power industry.

 Smart Communications v. Municipality of Malvar Batangas, G.R. No. 20449,


February 18, 2014

Fees for the construction of special projects such as cell sites were held as regulatory
fees because the main purpose of the ordinance imposing such fees was to regulate
certain construction activities like telecommunication towers and telephone lines.

o A license fee’s imposition must relate to the occupation or activity that so engages the public
interest in health, morals, safety and development as to require regulation for the protection and
promotion of such public interest.

 Compania general de Tabacos de Filipinas v City of Manila, G.R. No. L-16619,


June 29, 1963

The fee imposed by a city on liquor vendors for the privilege of selling liquor is a
license fee.

 Angeles University Foundation v City of Angeles, G.R. No. 189999, June 27,
2012

Building fees are not taxes or impositions upon property, but regulatory fees imposed
by a city for the activity of building or repairing a structure. Hence, a foundation which
is exempt from taxes is not exempt from the payment of building fees, as these are
not taxes in the first place.

o The imposition must also bear a reasonable relation to the probable expenses of regulation,
taking into account the costs of direct regulation and incidental consequences. A charged of fixed
sum which bears no relation at all to the cost of inspection and regulation may well be considered
a [Link]

 Chevron Philippines, Inc. v Bases Conversion Development Authority, G.R. No.


173863, September 15, 2010

Fees imposed on a per liter basis on fuel entering the Clark Special Economic Zone
were held to be regulatory fees because there was a reasonable relation between the
high volume of fuel brought into the zone and the greater extent of supervision and
inspection needed to monitor the fuel.

Tax as against special assessments


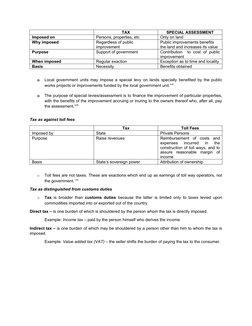
TAX SPECIAL ASSESSMENT
Imposed on Persons, properties, etc Only on land
Why imposed Regardless of public Public improvements benefits
improvement the land and increases its value
Purpose Support of government Contribution to cost of public
improvement
When imposed Regular exaction Exception as to time and locality
Basis Necessity Benefits obtained

o Local government units may impose a special levy on lands specially benefited by the public
works projects or improvements funded by the local government unit. xvii

o The purpose of special levies/assessment is to finance the improvement of particular properties,


with the benefits of the improvement accruing or inuring to the owners thereof who, after all, pay
the [Link]

Tax as against toll fees

Tax Toll Fees


Imposed by State Private Persons
Purpose Raise revenues Reimbursement of costs and
expenses incurred in the
construction of toll ways, and to
assure reasonable margin of
income
Basis State’s sovereign power Attribution of ownership

o Toll fees are not taxes. These are exactions which end up as earnings of toll way operators, not
the government. xix

Tax as distinguished from customs duties

o Tax is broader than customs duties because the latter is limited only to taxes levied upon
commodities imported into or exported out of the country.

Direct tax – is one burden of which is shouldered by the person whom the tax is directly imposed.

Example: Income tax – paid by the person himself who derives the income

Indirect tax – is one burden of which may be shouldered by a person other than him to whom the tax is
imposed.

Example: Value added tax (VAT) – the seller shifts the burden of paying the tax to the consumer.
i
71 Am. Jur 34
ii
Tax Made less taxing: A Reviewer with Codals and Cases, Ignatius Michael D. Ingles, 2018, 2 nd Edition
iii
Commissioner of Internal Revenue vs. Algue Inc. L-28896, Feb., 1988.

iv
"Cooley's definition," 1 Cooley 62
v
Tax Principles and Remedies, Justice Japar B. Dimaampao, 5 th Edition
vi
Vera v. Fernandez, L-31364, March 30, 1979
vii
I Cooley 68
viii
PCGG vs Cojuangco, GR. NO. 147062, Dec. 14, 2001
ix
Lutz vs. Araneta, GR. No. L-7859, Dec 22, 1955
x
Gomez vs. Palomar GR. No. L-23645, Oct 29, 1968.

xi
Bull v. United States, 295 U.S. 247.
xii
Law of Basic Taxation in the Philippines, Benjamin B. Aban, 1932-1997, Revised Edition, Fifth printing
xiii
Tax Made less taxing: A Reviewer with Codals and Cases, Ignatius Michael D. Ingles, 2018, 2nd Edition
xiv
Victoria Milling Co., Inc. vs Municipality of Victorias Negros Occidental L-21183; Serafica vs. Treasurer of Ormoc City, et al L-24813
xv
Philippine Airlines vs. Edu et al, L-41383 superseding Republic vs. Philippine Rabbit Bus Liner Inc, L-26862
xvi
Progressive Development Corporation vs. Quezon City, G.R. No. L-36081, April 24, 1989
xvii
Book II, Title One of RA 7160, otherwise known as “Local Government Code of 1991. Sec. 40. Special Levy by Local Government Units -
A province, city or municipality may impose a special levy on the lands comprised within its territorial jurisdiction specially benefited by
public works projects or improvements funded by the local government unit concerned: Provided, however, That the special levy shall
not exceed sixty percent (60%) of the actual cost of such projects and improvements, including the costs of acquiring land and such other
real property in connection therewith: Provided, further, That the special levy shall not apply to lands exempt from basic real property
tax and the remainder of the land portions of which have been donated to the local government unit concerned for the construction of
such projects or improvements.

xviii
Republic of the Philippines vs. Bacolod-Murcia Milling Co., G.R. No. L-19824, July 9, 1966
xix
Diaz vs . Secretary of Finance, G.R. No. 193007, July 19, 2011

Common questions

Powered by AI

Taxes are primarily imposed to raise revenue and are levied as sovereign powers of the state. In contrast, license fees are regulatory, imposed under the state's police power for specific activities like selling liquor or constructing telecommunication infrastructure, primarily to regulate rather than generate revenue. Special assessments are imposed on land only when it is specially benefited by public improvements to finance such improvements. Toll fees, imposed by private entities, are used to recover costs and assure reasonable income. Unlike taxes, toll fees do not end up as government revenue but as earnings of the operators .

A tax is broad, encompassing various exactions for revenue and public service funding, while customs duties are specific taxes on commodities crossing national borders. These differences affect international trade policy by allowing customs duties to be strategically implemented as trade barriers or facilitators, influencing global commerce patterns, and forming part of diplomatic trade agreements, highlighting their role in protecting domestic industries and adjusting foreign competition .

Taxation is an act of laying a tax, used by the state to raise income to cover necessary government expenses. It involves an enforced proportional contribution imposed by the state in its sovereign capacity, not founded on contract or agreement. Taxes are levied for public purposes and aimed at ensuring uniformity and apportionment of government burdens. They are considered the lifeblood of the State, critical for its operation and fulfilling its functions to promote the general welfare and protection of citizens. Taxes can also serve regulatory purposes, such as those on excise or privilege taxes, and as a police power to ensure the general welfare .

Taxes are not considered contracts or agreements because they are unilaterally imposed by the state, independent of taxpayers' consent, reflecting the compulsory nature rooted in state sovereignty. This setting implies taxpayer compliance is obligatory, enacted through law without mutual negotiation or consent, demanding automatic taxpayer obligations and legal recourse upon noncompliance, reinforcing the state's authority in revenue generation .

Taxation can promote general welfare by funding public services and regulatory schemes that enhance citizens' quality of life. Examples include excise taxes on tobacco and alcohol, aimed at controlling consumption for public health, or taxes used as implements of police powers to support development initiatives that improve living standards. The Supreme Court has recognized taxation's role as essential for governmental functions that indirectly boost citizens' moral and material well-being .

The power of taxation is inherently linked with state sovereignty, allowing the state to demand contributions for public purposes. It places constitutional constraints, requiring taxation power to be exercised through legislative statutes, rather than by the executive or judiciary branches. This delineates a clear separation of powers, ensuring that tax laws are democratically enacted and enforced according to public needs and calculated legislative processes .

Proportionality in taxation ensures fairness by requiring that taxes are levied based on an individual's ability to pay, promoting equitable distribution of tax burdens. Challenges to this principle may arise in cases of perceived fiscal inequality, where specific groups feel overburdened, or disparities emerge in tax code interpretations, causing sectors to perceive favoritism or discrimination not justified by economic rationales or needs .

The key elements that define a tax include it being an enforced proportional contribution from persons and properties, imposed by the state by virtue of its sovereignty, and levied primarily for government support. These elements inform its implementation by requiring legislative enactment for uniform and proportionate enforcement, ensuring equitable contribution from entities within the state's jurisdiction. Taxes are personal to the taxpayer, notable because responsibilities cannot be transferred to stakeholders in case of corporate delinquency, highlighting strict adherence to the principle of direct burden .

The legal framework ensures that taxation is equitable by imposing taxes proportionally based on one's ability to pay, thereby intending uniformity of contribution. The courts have held that any apparent inequality arising from selecting certain classes for taxation or exemption does not infringe constitutional protections, because the state has the freedom to determine who or what is subject to taxation or exemption. This ensures taxes are levied fairly and according to the law .

A state cannot impose taxes beyond its jurisdiction, as taxation is limited to persons and properties under its sway. This principle is upheld by ensuring the entity taxed must be within the jurisdiction and subject to the state's sovereignty. Jurisdiction is crucial, and extraterritorial taxation is illegal, reflecting constitutional limits where federal principles impede states from reaching into other territories for tax imposition .
I.
GENERAL PRINCIPLES
A. Concept and Purpose of Taxation
1. Definition
Taxation is the act of laying a tax. It is a process o
class for taxation or exemption infringe no constitutional exemptionix, (2) As the State has the power to
determine subjects
Tax is imposed for revenue purposes, whereas a license fee is imposed for regulatory purposes. The
imposition is tax when the
TAX
SPECIAL ASSESSMENT
Imposed on
Persons, properties, etc
Only on land
Why imposed
Regardless of public 
improvement
Public
i 71 Am. Jur 34
ii Tax Made less taxing: A Reviewer with Codals and Cases, Ignatius Michael D. Ingles, 2018, 2nd Edition
iii

You might also like